Rental yield in Kharadi: what a 2 BHK actually returns
The gross yield is about 3.5 per cent. The net is lower, and the gap between the two is where most investment cases quietly fall apart. Here is the arithmetic in full.
Blackstone Realty · 8 August 2026 · 7 min read
Kharadi is sold to investors on rental demand, and the rental demand is real. Sixty to eighty thousand people work at EON alone, and a large share of them rent within a few kilometres.
Real demand and a good return are different questions though, and only one of them gets answered in a sales lounge.
The gross number
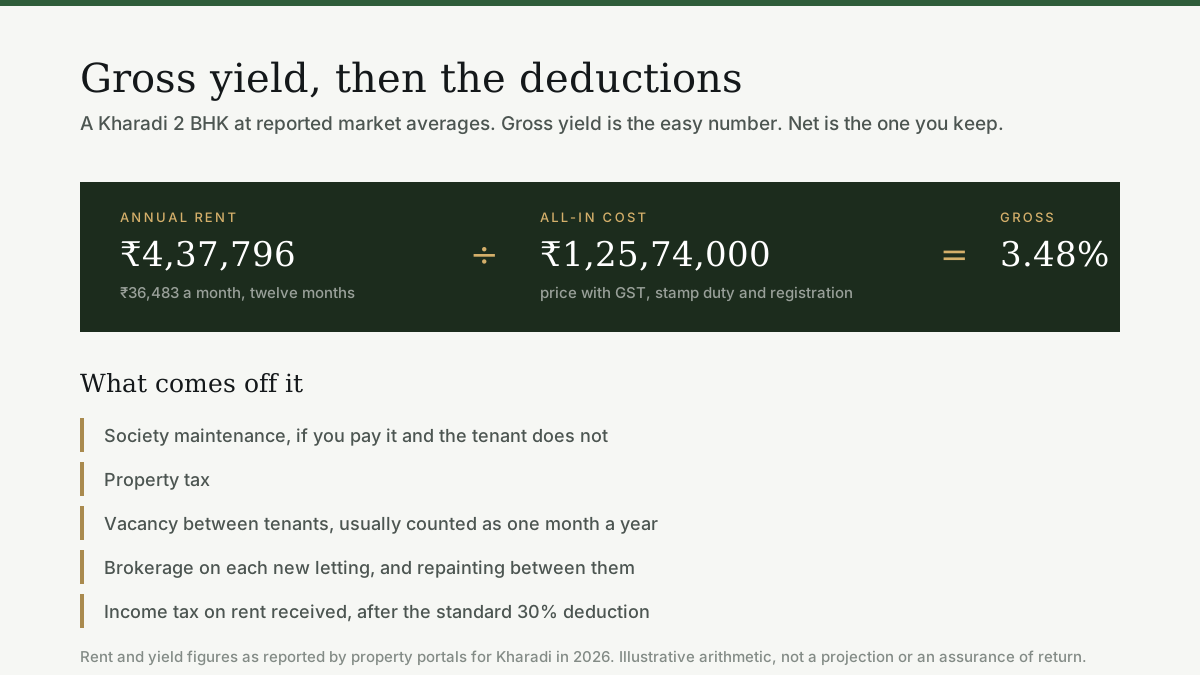
Reported averages for Kharadi put a 2 BHK at around ₹36,483 a month, which is ₹4,37,796 a year. Portals quote the locality yield at about 3.97 per cent.
That 3.97 per cent is calculated against the property price. Calculate it against what the property actually costs you and the number moves.
Agreement value ₹1,12,00,000, plus GST, stamp duty and registration: ₹1,25,74,000
Annual rent ₹4,37,796
Gross yield: 3.48 per cent
Half a percentage point sounds small. It is the difference between the number in the pitch and the number in your bank account, and it exists purely because one calculation ignores about ₹13.74 lakh of unavoidable cost.
What comes off the gross
Five deductions, all of them ordinary and all of them routinely left out.
Society maintenance. On an amenity-heavy project this is significant, and in most Pune lettings the owner carries it rather than the tenant.
Property tax. Annual, and payable whether or not the flat is let.
Vacancy. Convention is to assume one month a year between tenants. That is eight per cent of your rental income before anything else happens.
Brokerage and repainting on each new letting. Typically a month’s rent to the broker, plus the cost of making the flat presentable again.
Income tax on rent received, after the standard thirty per cent deduction for repairs. At a thirty per cent marginal rate that is roughly twenty-one per cent of gross rent gone.
Work all five through and a 3.48 per cent gross typically lands somewhere near 2 per cent net. That is the honest number to compare against a fixed deposit.
The pre-launch complication
A pre-launch flat produces no rent at all until possession. On a 2030 possession, that is four years of paying and nothing coming back.
During those four years you carry:
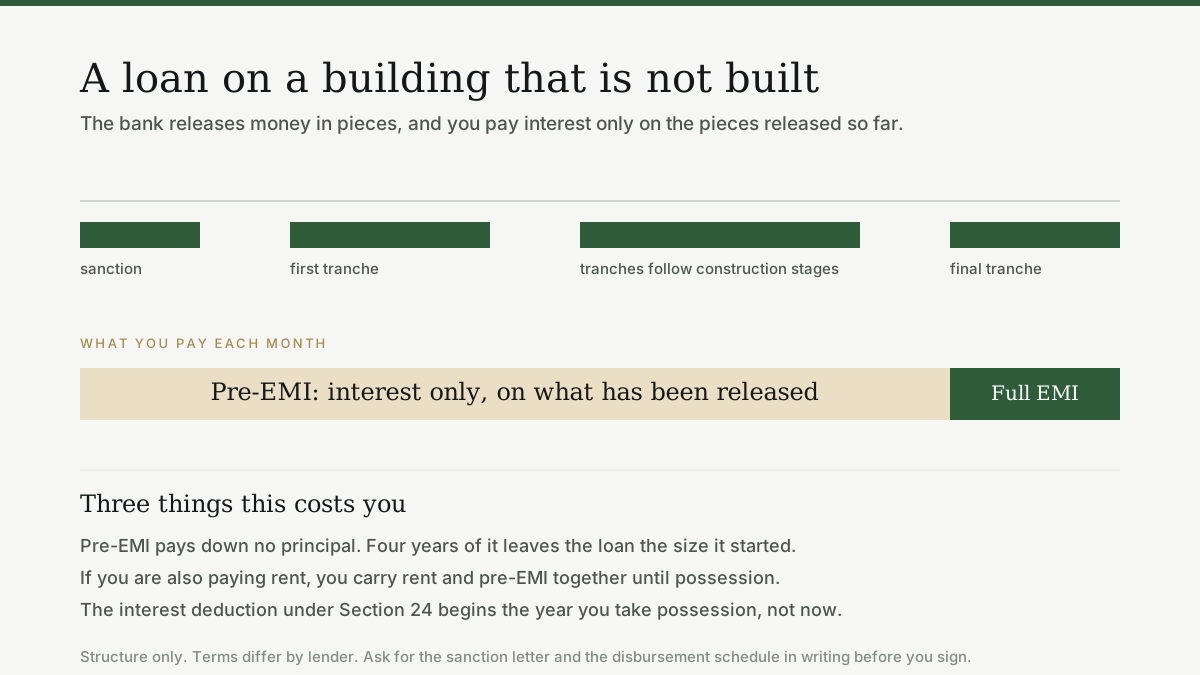
Pre-EMI interest on whatever the bank has disbursed so far, which pays down no principal
Your own rent, if you are living somewhere else
No tax deduction on the interest, because Section 24 relief starts the year you take possession
The compensation is the price. You are buying at a pre-launch rate rather than a completed one, and the discount is meant to pay you for those four years. Whether it does is the entire investment question, and it is answerable with a spreadsheet rather than a brochure.
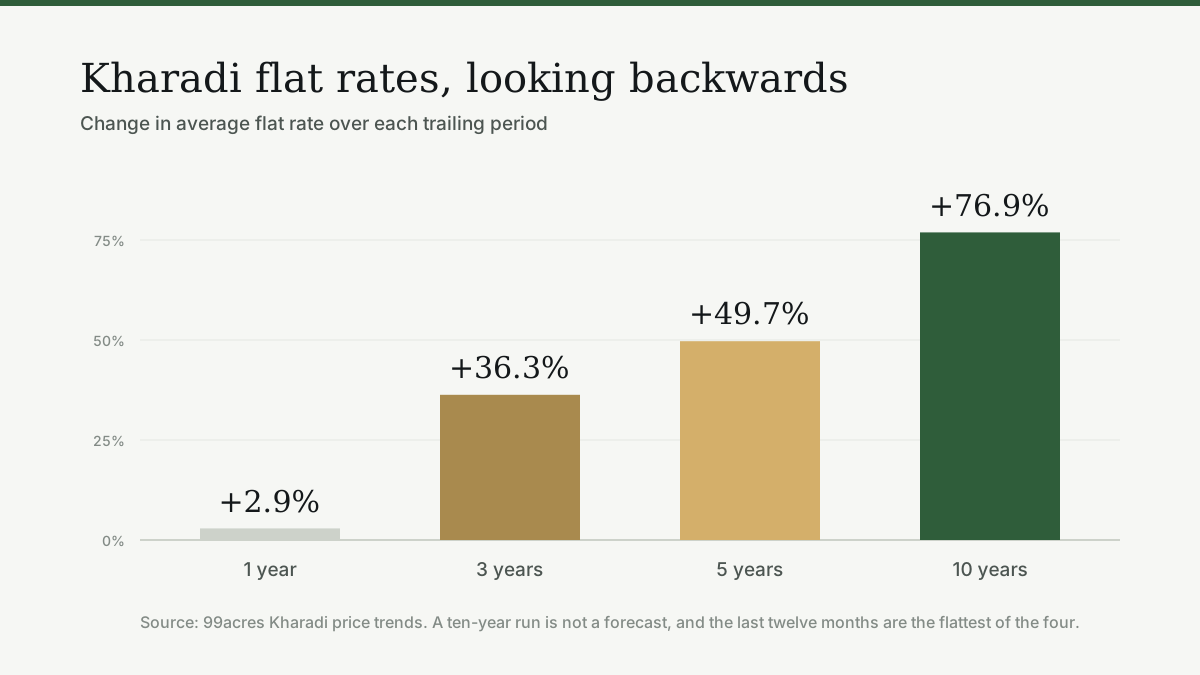
Trailing rate change in Kharadi, as published by 99acres. Capital gain here has been large and lumpy rather than steady. · Illustration
Where the return actually comes from
Kharadi rates rose 76.9 per cent over ten years and 49.7 per cent over five. Over the last twelve months they rose 2.9 per cent.
That is the real shape of it. The capital gain has been large and it has been lumpy, arriving in bursts when the office market expanded and pausing in between. Anyone modelling a smooth eight to twelve per cent a year is modelling something this market has not actually done.
Three questions before you treat it as an investment
What is the net yield after every deduction above? If nobody will put a number on it, that is the answer.
What does the same money return elsewhere, with no vacancy risk, no tenant and no four-year wait?
Can you carry the pre-EMI and your own rent together for four years if possession slips by twelve months? Because sometimes it does.
None of this makes Kharadi a bad buy. It makes it a home with a rental option attached, which is a perfectly good thing to be, and a very different thing from what the yield chart implies.
Booking a pre-launch flat: the sequence and the ten per cent rule
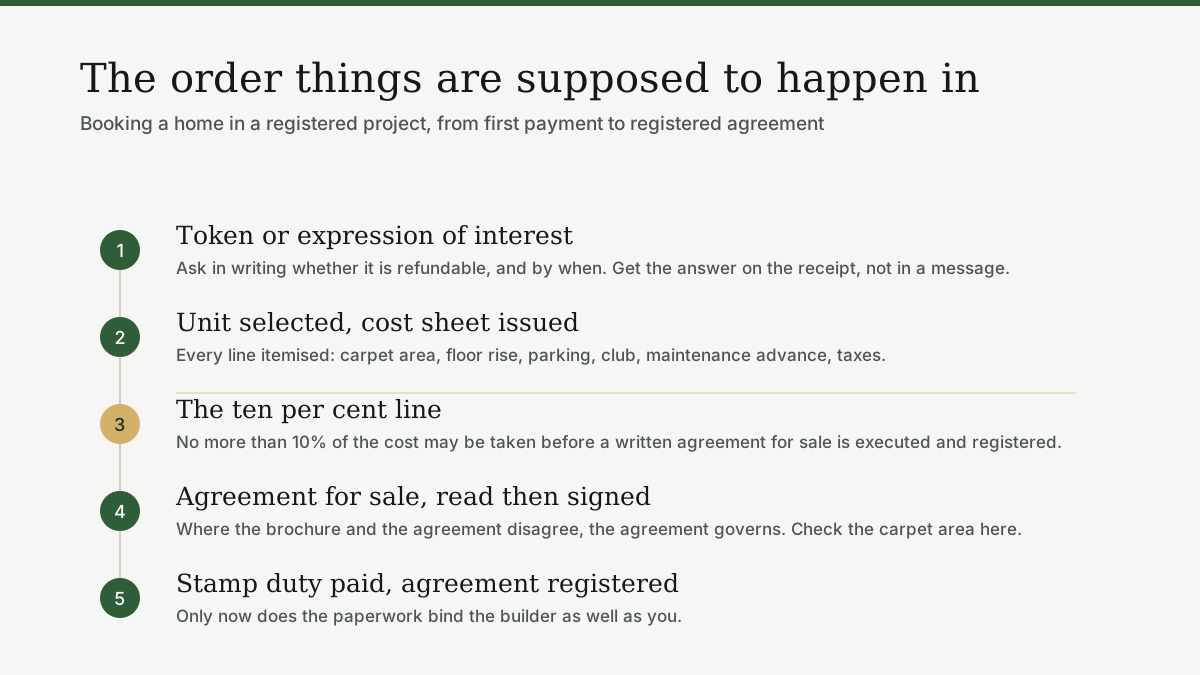
Five steps between the first payment and a registered agreement, the documents to collect at each, and the one legal limit that decides how much anyone can take from you before it.
Part disbursement, pre-EMI, and a tax deduction that does not start until you have the keys. What a loan on a 2030 possession actually costs you between now and then.
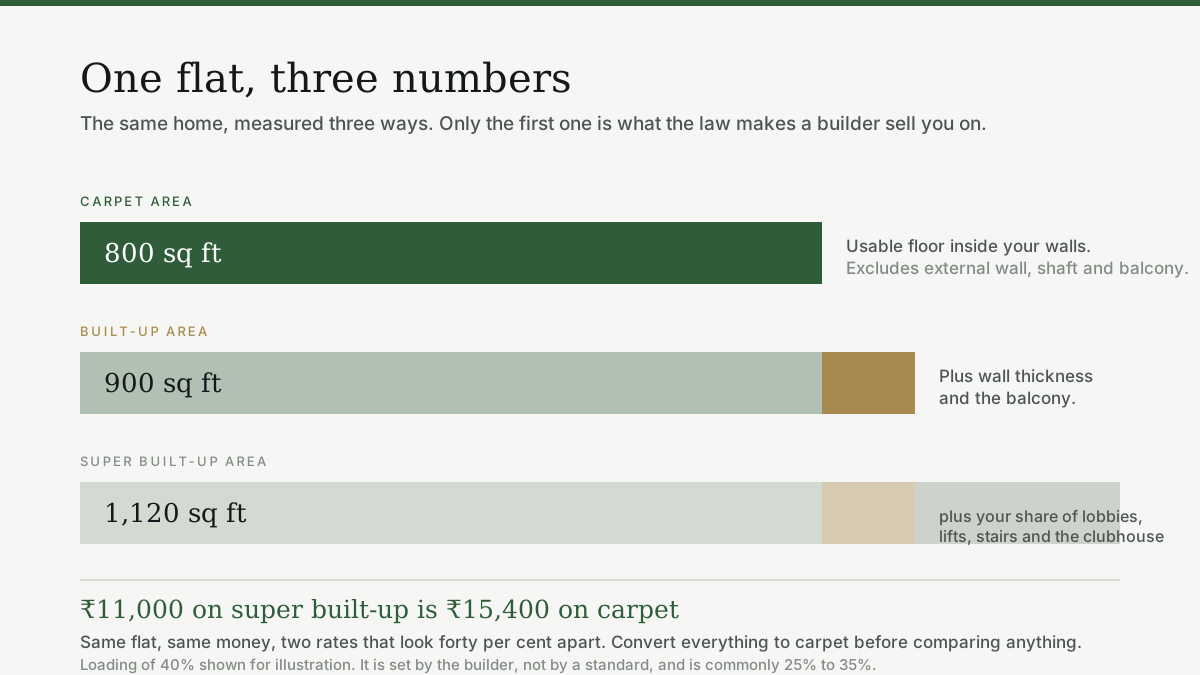
Carpet, built-up and super built-up: which number you are actually buying
Three area figures, one flat, and a gap between them that can reach thirty per cent. Only one of the three is what the law makes the builder sell you on.